There’s a conversation happening in boardrooms and strategy calls across the globe right now, and it sounds less like excitement than exhaustion. Teams that adopted AI tools to move faster are moving — but they’re spending an increasing amount of that saved time doing something nobody advertised:
checking the AI’s work.
Welcome to the real cost of the machine economy. Not the compute bill.
Not the subscription stack.
The cognitive one.
Trend Report
The Verification Tax: AI’s Hidden Labour Cost
Defining the Concept
The Verification Tax refers to the growing proportion of working time leaders and knowledge workers spend auditing, fact-checking, and correcting AI-generated outputs — often approaching the same hours that would have been spent producing the work manually.
The promise of generative AI was throughput. More content, faster strategy, leaner teams. What the pitch decks didn’t include was the hidden line item:
someone still has to read everything the model writes.
By 2026, reports of “AI burnout” are no longer anecdotal. Leaders describe a peculiar fatigue — not from doing more, but from the constant vigilance required when machines do the doing. A draft is not a deliverable. A summary is not a source. The gap between those two things?
That’s where the Verification Tax lives.
The model doesn’t get tired of being wrong.
You get tired of catching it.
For B2B brands, this has operational consequence.
Marketing and comms teams that expanded their content velocity using AI tools are now discovering that the editorial oversight function — the one they assumed would shrink — has in some cases grown.
The tax compounds at scale:
more content means more checking, and more checking means more skilled hours, which quietly erodes the productivity gains that justified the tools in the first place.
The strategic question isn’t whether to use AI.
It’s whether your team has built a verification layer that’s efficient enough not to cancel out the benefit.
The Verification Tax is the growing proportion of working time that knowledge workers and leaders spend auditing, fact-checking, and correcting AI-generated outputs.
Coined to describe a structural inefficiency in AI-augmented workflows, it occurs when the editorial oversight required to verify AI content approaches — or exceeds — the time saved by generating it. By 2026, the Verification Tax has become a measurable operational cost for B2B marketing and communications teams that expanded content velocity using generative AI tools.
Search & Discoverability
GEO: You’re No Longer Bidding for Clicks
For two decades, digital marketing operated on a known equation: identify the keywords your audience searches, bid for or earn placement in those results, capture the click. That equation is breaking down.
Generative Engine Optimization (GEO) is what replaces it — a discipline focused not on ranking in a list of blue links, but on being cited by an AI when a user asks a question conversationally. Google’s AI Overviews, Perplexity, Gemini’s integrated answer experiences — these surfaces don’t return ten results.
They return one synthesised answer. And that answer cites sources it has been trained to trust.
The implication for brand strategy is fundamental. You are no longer trying to outrank a competitor for a keyword.
You are trying to ensure that when a model constructs its answer about your category, your brand’s assets — your articles, your product data, your entity graph — are among the inputs the model draws from.
1 Synthesised answer, not ten links. That’s the new real estate.
GEO Feed the model high-quality, structured brand assets — or stay invisible.
↓ Keyword bidding is declining as a primary discovery mechanism.
The practical shift:
brands are now investing in entity reinforcement — ensuring their organisation, founders, products, and expertise appear consistently and accurately across structured data, authoritative editorial, and AI-accessible content formats.
Schema markup, long-form thought leadership, consistent brand entity signals.
These are the new currency of discoverability.
If your brand isn’t actively feeding the machine quality material, the machine will fill the gap with someone else’s narrative about you.
Consumer Experience
Hyper-Personalization: Expectation Has Moved
Personalization used to be a differentiator.
Showing a customer their name in a welcome email was, not long ago, considered sophisticated.
That bar has moved — considerably, and quickly.
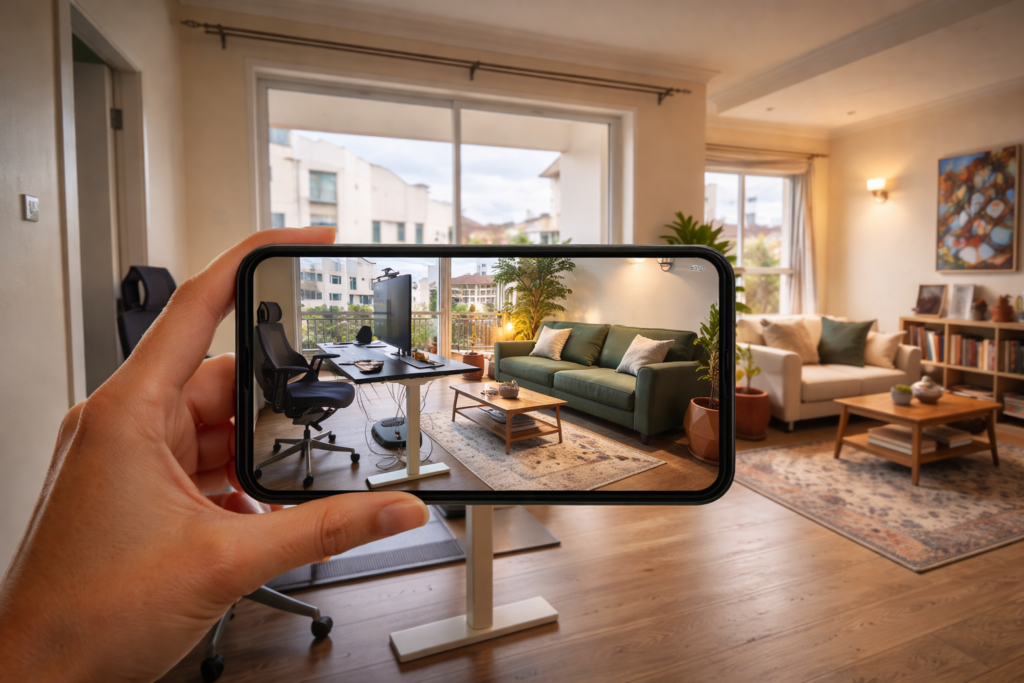
Tools like IKEA’s Kreativ — which allows customers to digitally furnish their actual rooms using their phone camera — represent a shift in what personalization means.
It is no longer segmented messaging. It is the brand entering the physical context of the customer’s life and responding to what it finds there.
YouTube’s personalised experiences are building similar muscle:
AI surfaces that don’t just know your watch history, but begin constructing media experiences specific to your moment — your language, your location, your recent behaviour, the time of day.
Personalisation is no longer about using someone’s name. It’s about demonstrating that you understand their actual situation.
For B2B brands and SMEs, the challenge is contextual: you may not have IKEA’s engineering budget, but your customers are being trained by these experiences to expect relevance.
A generic email sequence feels worse in 2026 than it did in 2022 — not because it got worse, but because the reference points shifted.
The strategic response is not to replicate the technology.
It’s to tighten your data capture, segment more deliberately, and make your touchpoints feel responsive to the actual stage the customer is at — rather than where your funnel assumes they should be.
Consumer Behaviour
Present Wellbeing: Why Your Loyalty Programme Feels Outdated
Defining the Concept
Present Wellbeing describes a documented consumer behaviour shift in which individuals increasingly prioritise smaller, immediate rewards and experiences over long-term accumulation — choosing present enjoyment over future security, smaller treats over large deferred goals.
This is the consumer psychology behind a now-familiar observation:
people who objectively cannot afford a holiday are booking short trips. People who have not saved a house deposit are spending on weekly experiences.
This is not irrationality — it is a recalibration of what “reward” means after years of postponed life.
For loyalty programme designers and retention marketers, the consequence is direct. Traditional points architectures — accumulate slowly, redeem eventually, get the big prize — are built on an assumption of deferred gratification that fewer customers are emotionally available for.
The programmes gaining traction in 2026 are those offering immediate, tangible, low-friction rewards. Instant discounts over accumulated points.
Experience unlocks over merchandise catalogues.
Status signals that are visible and usable now, not next quarter.
The insight for African markets specifically:
in contexts where economic uncertainty is structural and long-term planning feels aspirational rather than practical, Present Wellbeing behaviour has arguably always been the dominant mode.
The global trends are, in many ways, catching up to a consumer psychology that was already here.
E-Commerce
Amazon vs. TikTok Shop: The Discovery Layer Has Shifted
Amazon’s dominance in e-commerce has long rested on two pillars: trust and fulfilment infrastructure. When you need something, you go to Amazon. That behaviour is being disrupted — not at the checkout, but earlier.
At the point of discovery.
Shein and TikTok Shop have built their market position not by out-logisticsing Amazon, but by collapsing the distance between content and commerce.
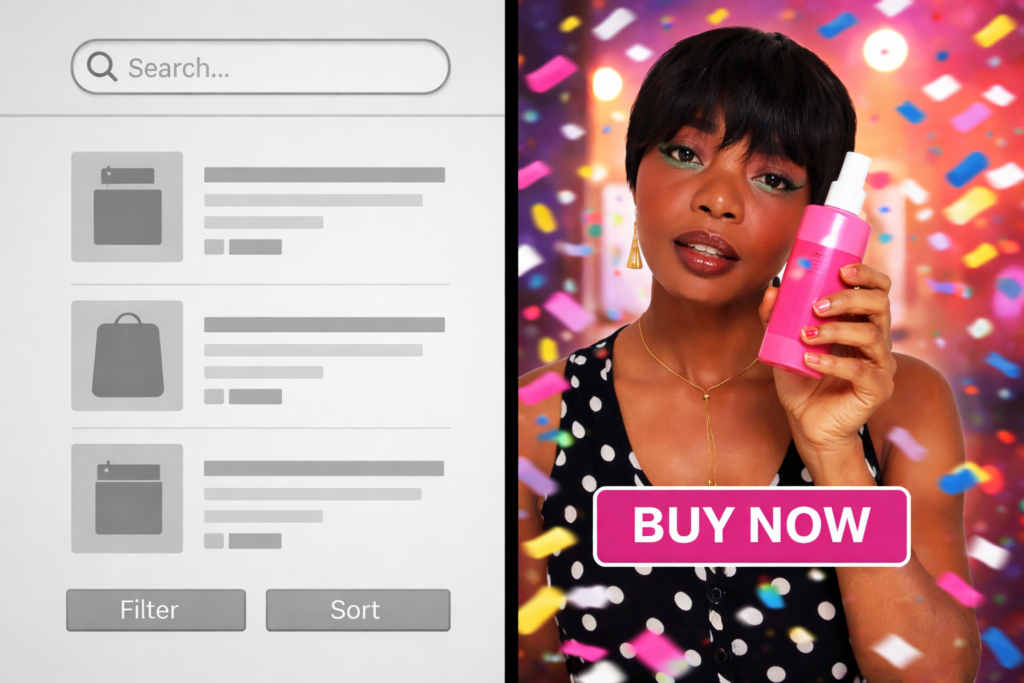
On TikTok Shop, a product is discovered inside entertainment — a video, a creator, a moment of genuine delight or curiosity — and purchased without leaving that context. The intent is manufactured in-platform, not imported from a search query.
This is a structurally different model.
Amazon captures existing demand. TikTok Shop and Shein create demand — and then immediately convert it. The result is that an entire category of discretionary purchase now begins and ends on a short-video platform, with Amazon never in the consideration set.
TikTok
Manufactures demand inside entertainment. Discovery and purchase collapse into one moment.
Amazon
Captures existing demand. Its search infrastructure dominates intent-led purchase.
For brand strategists, the operational question is which discovery layer your category lives in. Products that require explanation or trust still travel through Amazon-style intent search.
Products that create desire visually — fashion, beauty, homeware, food — are increasingly born on social commerce.
For African market operators:
the TikTok Shop playbook is directionally relevant even where the platform itself isn’t the primary channel.
Social-to-checkout behaviour is accelerating across Instagram, WhatsApp, and emerging platforms. The principle — manufacture desire, then remove friction from conversion — travels across contexts.
The Machine Runs on Your Assets
What connects these five trends is a single underlying dynamic:
the AI economy does not replace human input — it amplifies whatever you bring to it.
If you bring in low-quality brand assets, GEO surfaces a weak brand. If you deploy AI without a verification culture, you accumulate the Verification Tax. If you treat hyper-personalization as a technology problem rather than a data and empathy problem, you get the infrastructure without the results.
If your loyalty architecture was built on old assumptions about how people relate to the future, it will feel increasingly hollow to a consumer who lives in the present.
And if you’re still building your entire discovery strategy around a single platform — any platform — the TikTok Shop story is a reminder that the channel your customer moves through can change faster than your quarterly plan.
The machine is powerful.
But it runs on your clarity, your assets, and your willingness to stay in the conversation about what it’s actually costing you — not just in subscriptions, but in attention, trust, and time.
That accounting is still a human job.
Generative Engine Optimization (GEO) is a brand discoverability discipline focused on ensuring a brand’s assets — articles, product data, structured content, and entity signals — are cited by AI engines when users ask questions conversationally.
Unlike traditional SEO, which targets keyword rankings in a list of search results, GEO targets inclusion in a single synthesised AI-generated answer.
Key GEO tactics include schema markup, entity reinforcement across structured data, long-form thought leadership, and consistent brand signals across AI-accessible content formats.
Present Wellbeing is a documented consumer behaviour pattern in which individuals prioritise smaller, immediate rewards and experiences over long-term accumulation.
Characterised by a preference for present enjoyment over deferred gratification, it explains why consumers who objectively cannot afford large purchases are spending on immediate experiences.
In loyalty programme design, Present Wellbeing behaviour correlates with declining engagement in traditional points-accumulation models and rising preference for instant discounts, experience unlocks, and status signals that are usable immediately.
Amazon and TikTok Shop operate on structurally different discovery models. Amazon captures existing demand: users arrive with purchase intent and search for products within an established trust and fulfilment infrastructure.
TikTok Shop manufactures demand: products are discovered inside entertainment — a video, a creator, a moment of curiosity — and purchased without leaving that context.
The result is that a growing category of discretionary purchase now begins and ends on a short-video platform, with Amazon never entering the consideration set.
Brands must assess which discovery layer their category inhabits to determine their platform strategy.
Brands adapting to AI-driven discovery in 2026 must invest in three interconnected areas.
First, entity reinforcement: ensuring the brand, its founders, products, and expertise appear consistently and accurately across structured data and authoritative editorial.
Second, GEO-compatible content: long-form thought leadership, schema markup, and AI-accessible formats that give generative engines quality material to draw from.
Third, verification infrastructure: an editorial oversight layer efficient enough to validate AI-generated content without cancelling the productivity gains that justified the tools. The brands most exposed in the AI economy are those with thin digital footprints and no verification culture.
Leave a Reply